
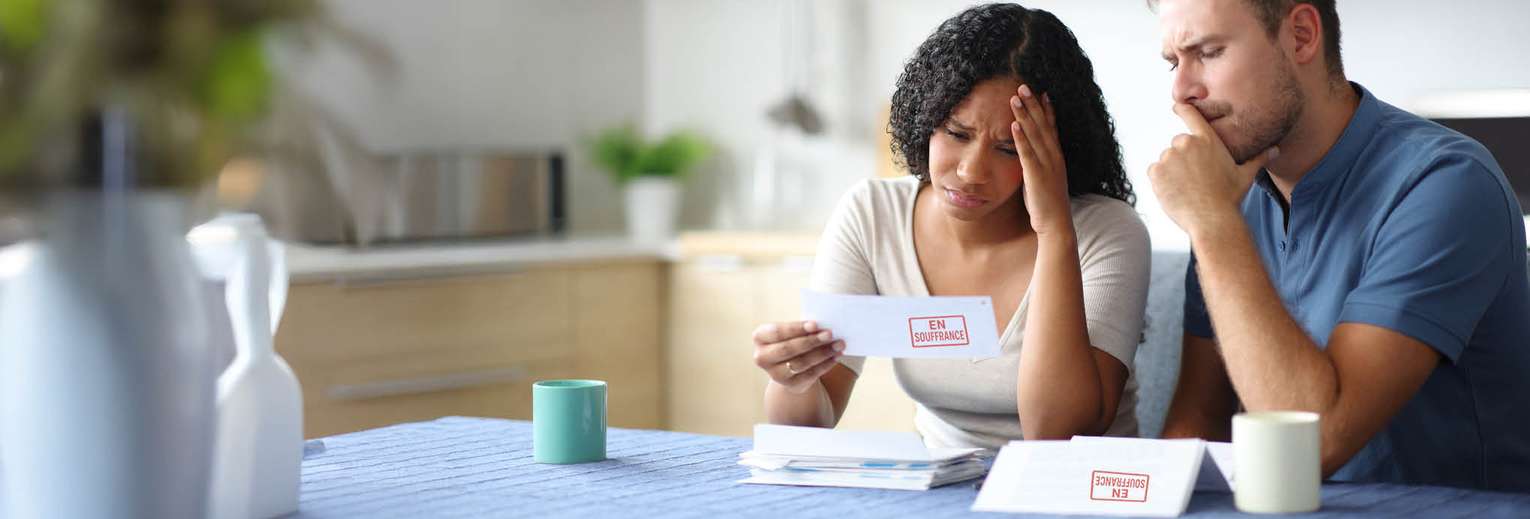
Financial stress has a way of following us. It can be there when we wake up, when another bill arrives, or when we are trying to fall asleep at night. For Canadians struggling with debt, the uncertainty can sometimes feel as difficult as the debt itself.
Will I be able to make the next payment? What happens if an unexpected expense comes up? How long can I keep doing this? If those questions sound familiar, you are not alone. Experiencing financial difficulty is not a personal failure.
Debt problems can develop for many reasons—a change in employment, illness, separation, caregiving responsibilities, housing costs, unexpected expenses or simply not having enough room in the household budget. The important thing to remember is that financial problems can be addressed, and you do not have to wait for a crisis before asking for help.
When Financial Stress Becomes More Than a Money Problem
Debt is measured in dollars, but its impact can extend well beyond your bank account. Constantly worrying about payments can take up significant mental and emotional energy. You may find yourself thinking about money at work, avoiding conversations about finances at home or losing sleep trying to decide what to pay first.
That stress can also make financial decisions more difficult. When everything feels urgent, it can be harder to step back and look at the bigger picture.
How Financial Stress Can Become a Cycle
Financial difficulties rarely appear overnight. A tight household budget may lead to using a credit card for groceries or a line of credit for an unexpected expense. Over time, more income goes toward debt payments, leaving less for everyday expenses.
The cycle can look like this: Financial pressure → reliance on credit → higher payments → less room in the budget → more stress → additional borrowing. When the situation becomes overwhelming, it can also be tempting to avoid opening bills, checking balances or answering calls from creditors. The goal is not to solve everything at once. The first step is simply understanding where you stand.
Recognizing the Warning Signs
There is no single amount of debt that means someone needs professional help. Instead, pay attention to how debt is affecting your monthly finances.
It may be time to seek advice if you are:
- using credit regularly for groceries or necessities;
- borrowing from one source to pay another;
- making minimum payments without reducing balances;
- falling behind on bills;
- receiving collection calls or notices;
- unable to see a realistic way of repaying your debt; or
- finding that financial worries are affecting your day-to-day well-being.
You do not need to wait until all of these things are happening. Getting advice earlier may give you more options.
Start by Replacing Uncertainty With Information
Begin by writing down your monthly income, essential expenses, debts and required payments. Look at the numbers without judging yourself. The purpose is not to ask what you should have done differently. It is to understand what you can do next.
If the numbers show that your income cannot realistically cover your living expenses and debt payments, acknowledge that. Trying harder cannot fix a mathematical shortfall.
You may also want to contact creditors early if you expect to miss payments and be cautious about using additional borrowing simply to keep existing debts current.
When Should You Speak With a Licensed Insolvency Trustee?
Many people assume you only speak with a Licensed Insolvency Trustee when you are ready to file for bankruptcy. That is a misconception. A Licensed Insolvency Trustee (LIT), can review your financial circumstances and explain the options that may be available to you.
Speaking with an LIT does not mean you are declaring bankruptcy or filing a consumer proposal. The purpose of the conversation is to understand your situation and determine what options make sense. Most LITs even provide the initial consultation free of charge.
Depending on your circumstances, those options could include changes to your budget, repaying creditors directly, consolidation or refinancing, credit counselling, a consumer proposal or bankruptcy.
Sometimes the most valuable outcome of a consultation is discovering that a formal insolvency proceeding is not necessary. Either way, having reliable information can replace some of the uncertainty.
Debt Does Not Define You
One of the most difficult things about financial stress is the shame that can accompany it. But debt does not define someone's character. Behind financial difficulty there may be job loss, illness, separation, family responsibilities, business challenges, unexpected expenses or simply a household budget that no longer works.
Instead of asking: “How did I let this happen?”
Try asking: “What can I do from here?”
You cannot change yesterday's circumstances, but you can understand today's situation and make informed decisions about tomorrow.
You Don't Have to Figure It Out Alone
Financial advice is not a substitute for mental-health care. If worries about money are significantly affecting your sleep, relationships, ability to function or overall well-being, consider speaking with a qualified health professional or trusted mental-health service.
Likewise, if debt is contributing to your stress, consider getting qualified financial advice rather than carrying the uncertainty alone. There is no shame in needing either kind of support—or both. You do not have to solve everything today. Sometimes the most important first step is simply deciding that you no longer have to figure it out alone.